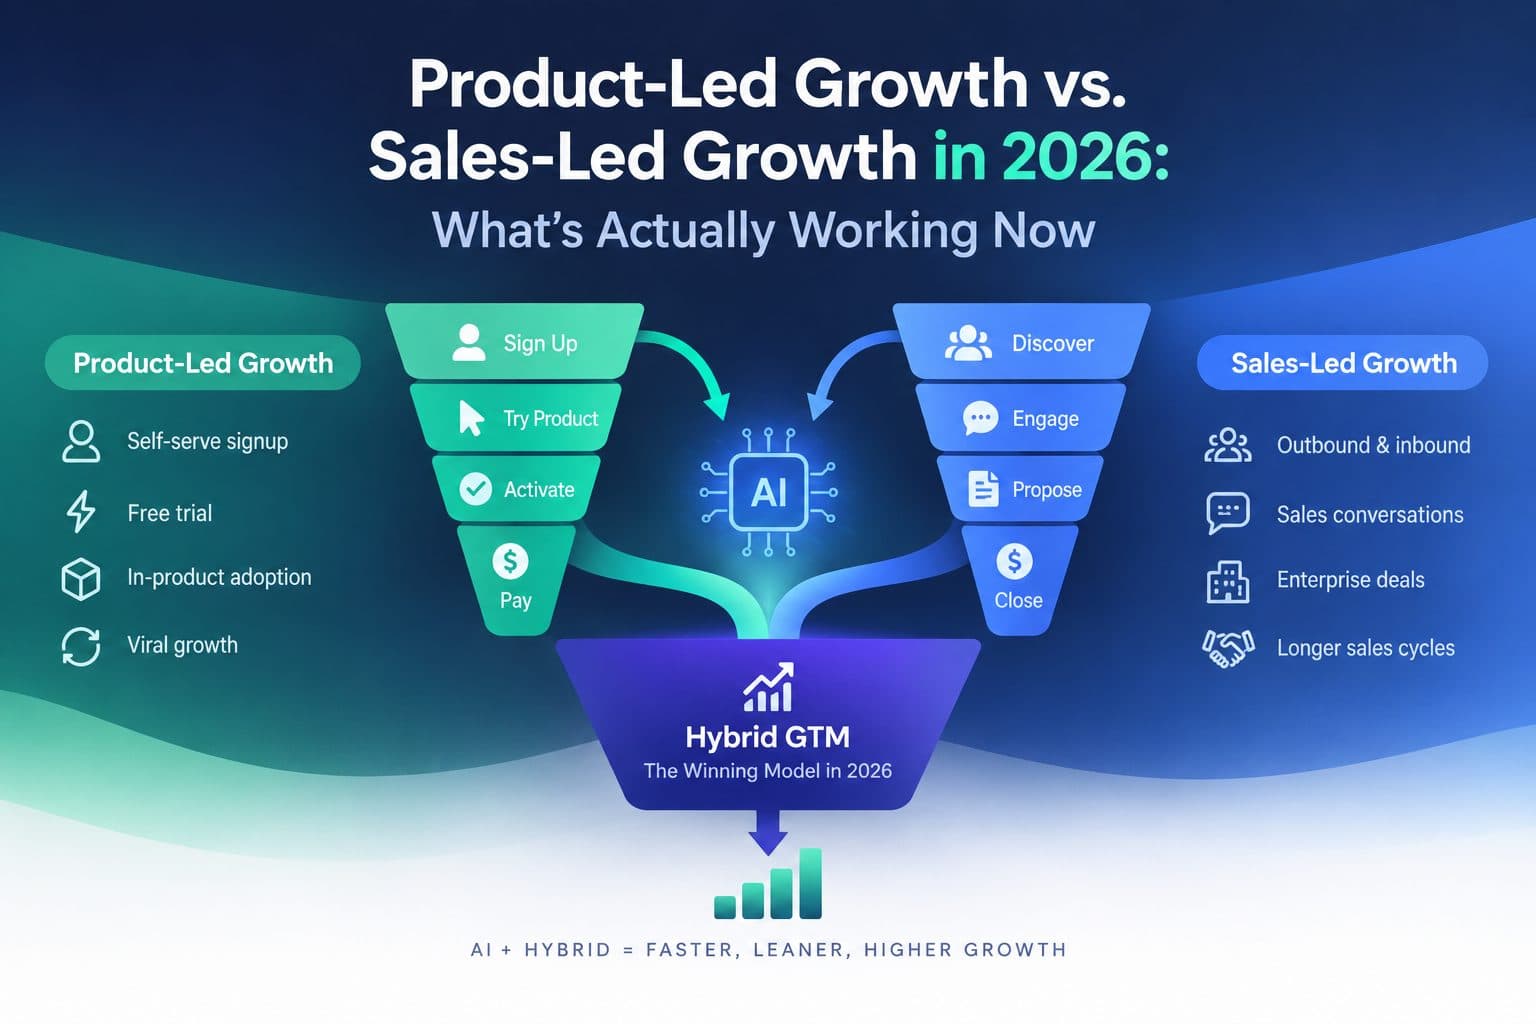
Product-Led Growth vs. Sales-Led Growth in 2026: What's Actually Working Now
The product-led-growth-versus-sales-led-growth debate is mostly settled: roughly 60% of B2B SaaS companies now run a hybrid of both, according to ICONIQ Growth's January 2026 survey of 150-plus B2B SaaS executives. The bigger, newer performance gap in the same data isn't PLG versus sales-led at all — it's AI-native companies converting free trials to paying customers at 56%, against 32% for traditional SaaS, a 24-point gap that dwarfs anything the PLG-versus-SLG framing on its own has produced in a decade of benchmarking.
The Old Question Has a Fairly Settled Answer
For years, "PLG or sales-led?" was treated as a binary strategic choice. The 2026 data says it mostly isn't, and hasn't been for a while. ICONIQ's benchmark shows around 60% of B2B SaaS companies running a hybrid motion, and separately, an OpenView 2024 SaaS Benchmarks analysis found hybrid PLG-plus-sales-assist companies hit their net revenue retention targets at a 67% rate, against 58% for pure-PLG companies — because hybrid companies apply sales-assist specifically to the accounts with the most expansion potential, while pure-PLG companies leave those same accounts to expand or churn on their own.
Contract size is still the strongest predictor of which blend makes sense. Across multiple 2026 benchmark sources, the pattern is consistent: PLG dominates for annual contract values (ACV) under $5,000, where fast self-serve onboarding and low-touch virality do most of the work; sales-led and account-based motions take over above roughly $25,000 ACV, where multi-stakeholder buying committees and custom implementation make a pure self-serve path impractical; and the $5,000–$25,000 band is where hybrid motions — self-serve trial with a sales-assist layer for expansion or larger deals — perform best. None of this is new in structure. What's changed is how much of the actual performance variance it explains.
The Gap That Actually Matters Now
ICONIQ's most recent full survey cycle — 205 GTM executives in April 2025, followed by a 150-plus-executive update in January 2026 — found that AI-native companies convert free trials to paying customers at 56%, compared with 32% for traditional SaaS companies, a 24-percentage-point gap that the firm describes as widening rather than stabilizing. The same AI-forward companies posted higher quota attainment (61% versus 56%), shorter sales cycles (20 weeks versus 25), and lower cost per opportunity ($8,300 versus $8,700) than their traditional-SaaS peers — outperforming on essentially every efficiency metric ICONIQ tracked, regardless of whether the underlying motion was product-led or sales-led.
The efficiency gap shows up most starkly in headcount. ICONIQ's data found companies under $25M ARR with high AI adoption running go-to-market organizations roughly 38% leaner than lower-adoption peers, and a follow-up analysis of the January 2026 data found AI-embedded GTM organizations generating roughly twice the net new revenue per full-time employee compared to medium- and low-adoption companies, with management structures reported to be up to 9 times flatter. The most cited concrete example: Perplexity scaled to 5,000 enterprise customers with a five-person sales team — a ratio that would have been considered a rounding error a few years ago in either the PLG or sales-led playbook. In another company ICONIQ profiled, a single human paired with an AI customer success system covered the account workload of roughly 20 human CSMs, and a voice-based AI sales development rep was reported to handle more than 90% of one company's EMEA inbound lead qualification before routing to a human.
Why This Reframes the Original Question
The practical implication is that "PLG or sales-led" is no longer the variable doing the most work in a company's growth outcomes — "AI-embedded or not" is, and it cuts across both motions rather than favoring one. A sales-led enterprise company with AI-assisted qualification, forecasting, and proof-of-concept management can now move meaningfully faster and leaner than it could two years ago, without becoming product-led at all. ICONIQ's January 2026 data shows this directly: proof-of-concept-to-paid conversion improved from 36% to 50% year over year — a sales-led motion metric — which the firm attributes largely to AI tooling compressing the technical evaluation process, not to any shift toward self-serve.
That doesn't mean AI adoption is evenly distributed or uniformly successful. The same ICONIQ dataset shows AI-driven forecasting adoption sitting at only 38% even among surveyed companies, and separate research from McKinsey found only about 23% of organizations are actually scaling agentic AI in any business function, with Gartner projecting more than 40% of agentic AI projects will be cancelled by 2027 — largely due to governance built in after deployment rather than alongside it. The gap between companies capturing the AI-native advantage and companies still experimenting with it is at least as wide as the older PLG-versus-sales-led gap ever was.
What Hasn't Changed
Two structural PLG realities from before the AI shift are still holding, and still worth benchmarking against. Activation remains the dominant point of failure in self-serve motions: 40–60% of free users in a typical PLG funnel never reach the product's core "aha moment," according to OpenView's benchmark data, which labels these accounts "zombie users." Top-performing PLG companies target 40–60% activation rates, with best-in-class products reaching 70%-plus — yet only about a third of PLG companies actively track activation as a formal metric, which remains one of the clearest unclaimed improvement opportunities in the data regardless of how much AI a company has layered on top.
Product-qualified leads (PQLs) also continue to substantially outperform marketing-qualified leads as a sales signal: PQLs reportedly convert at 25–30%, against 5–10% for MQLs, a 3-to-5x advantage — though only about a quarter of PLG companies run a formal PQL framework to route the highest-intent self-serve users to a sales-assist touch at the right moment.
What This Means for a SaaS Team Choosing a GTM Motion Now
Stop treating PLG-versus-sales-led as the primary decision. Contract size still determines the right base motion (self-serve under ~$5K ACV, hybrid in the middle, sales-led or account-based above ~$25K), but the larger 2026 performance gap runs through AI adoption inside whichever motion you already run.
Measure AI-embedded GTM against the ICONIQ benchmarks, not vibes. A 56% versus 32% trial-to-paid gap and roughly double the revenue per GTM employee are concrete targets — if your AI tooling isn't moving conversion or headcount efficiency meaningfully, it's more likely bolted on than embedded.
Fix activation before adding AI on top of it. A 40–60% zombie-user rate in a self-serve funnel won't be solved by faster onboarding scripts alone; if fewer than half of signups reach real product value, that's the higher-leverage problem to address first.
Build the PQL-to-sales handoff deliberately. With PQLs converting 3–5x better than MQLs but only about a quarter of PLG companies formalizing that handoff, this remains one of the more overlooked, low-cost improvements available inside an already-hybrid motion.
Comments